Unbilled Revenue Disclosure and Audit Requirements for SaaS
Consumption-priced SaaS needs usage records, not invoices, to support its period-end balance.
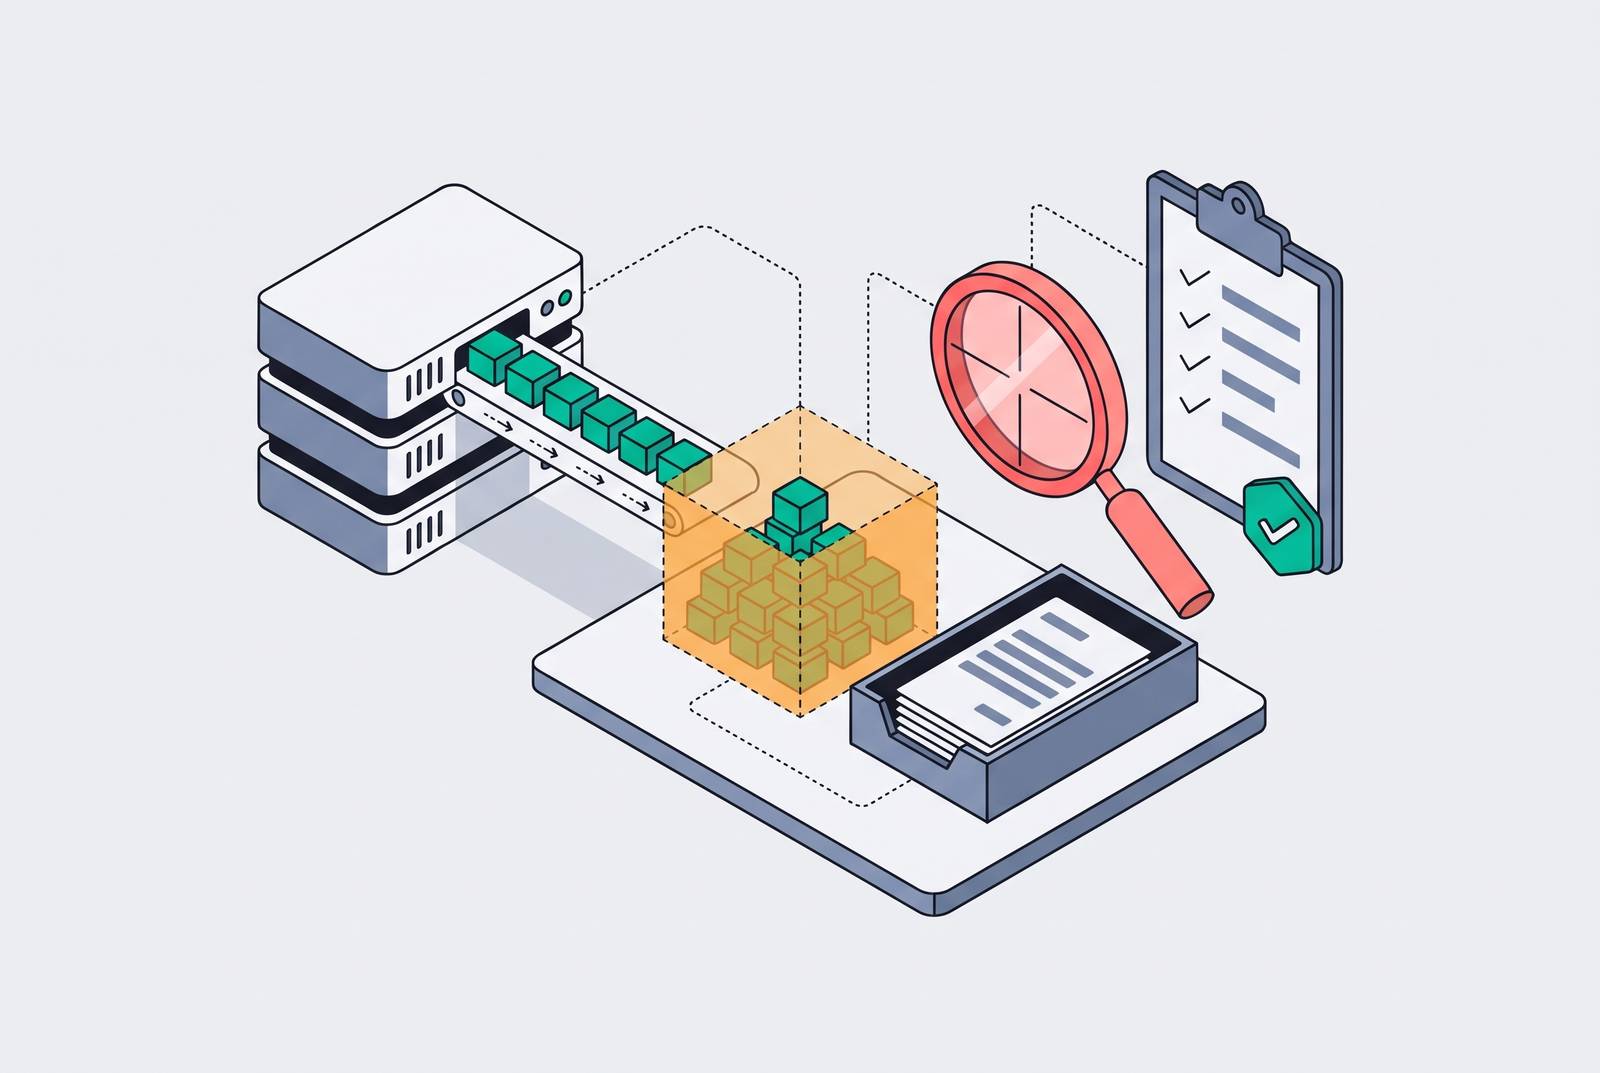
Unbilled revenue disclosure and audit requirements for consumption-priced SaaS depend on more than accounting policy. They also depend on whether the billing system can measure the service delivered through period-end. Under ASC 606, a defensible balance requires finance discipline and precise usage records, because an invoice produced later cannot substitute for evidence of what the company earned before the books closed.
Why consumption pricing turns unbilled revenue into an accounting problem, not just a timing difference
With a fixed subscription, finance knows the fee it has to spread across the service period. The gap between delivery and invoicing is usually narrow and mechanical. Consumption pricing removes that predictability from the amount earned. Usage accrues continuously, while invoices trail by days or weeks, so the closing balance reflects consumption that must be measured.
That difference changes the work required under ASC 606. The same five-step model applies, but the analytical weight shifts to determining the transaction price and recognizing revenue as performance obligations are satisfied. Finance must separate measured usage from estimates, apply the right constraint to variable consideration, and have evidence for the disclosures it makes. An error missed during the routine close can lead to a restatement, potentially surfacing during due diligence.
What unbilled revenue actually is under ASC 606 and how it arises in a metered product
Consider an AI API company with a monthly minimum covering a set volume of API calls and a per-call charge above that volume. In a month when calls exceed the commitment, the company totals the committed fee and the overage. The invoice follows in the next month. The full month’s earned revenue nevertheless belongs in the month of service, with a period-end debit to Unbilled Receivable and a credit to Revenue.
Unbilled revenue is therefore earned revenue that has not yet been invoiced. When the invoice is issued, the company debits Accounts Receivable and credits Unbilled Receivable. Revenue is not recognized a second time. Deferred revenue describes the opposite position, in which an amount has been billed but the service has not yet been earned, creating a liability.
For formal presentation, however, invoice status alone is insufficient to classify an asset as a contract asset or a receivable. ASC 606 draws a sharper distinction between the two. A contract asset is a right to consideration conditional on something other than the passage of time, such as satisfaction of another performance obligation. A receivable is unconditional, so an unbilled amount is not automatically a contract asset simply because an invoice has not been issued.
Usage delivered before period-end and invoiced in arrears is the common API and token-pricing case. Overages may also be calculated after the billing period closes. Annual seat true-ups can include usage from earlier periods, while minimum-commitment shortfalls billed at term-end can cover more than one period. Each pattern requires finance to connect the amount to the service period rather than treating the billing date as the recognition date.
How variable consideration and the constraint rule work for usage-based and AI-priced products
When fees are based on usage, variable consideration becomes part of the transaction price. Under ASC 606, the estimate uses either the expected value method or the most likely amount method and is updated each reporting period. Recognition is subject to the constraint on significant revenue reversals. For hybrid and minimum-commitment arrangements, that means the amount finance expects to collect is not necessarily the amount it can recognize.
Pure pay-as-you-go arrangements may be handled another way. The right-to-invoice practical expedient permits recognition of the amount the company has a right to invoice for consumption in the period when the arrangement qualifies. For a qualifying per-token arrangement, actual consumption supplies that amount without a forecast of future usage. The expedient does not make invoice timing the recognition trigger. Service delivered before period-end still belongs to that period, even if the invoice comes later.
The minimum-commitment example requires more judgment than pure pay-as-you-go. The practical position is to recognize committed minimums plus variable amounts supported by actual usage data, then expand the recognized estimate as comparable contract history accumulates. A volume tier or prepaid credit balance adds further estimation work. The statement that a company simply bills what was used does not resolve those contract terms.
Prepaid credits also require a separate judgment about breakage. Unused balances are not simply recognized when credits expire. Instead, historical redemption patterns support an estimated breakage rate, with estimated breakage recognized proportionally as an uplift alongside actual usage. Each reporting period, auditors check how accurate the past estimates of variable consideration have been. If estimates have been materially wrong over time, the constraint must tighten, making estimation history a direct input to the audit.
The period-end close problem and why metering infrastructure determines whether unbilled revenue is accurate
The accounting requirement creates a precise operational requirement at close. To close the books on March 31, finance needs usage totals through 11:59 PM on March 31, a cut-off distinct from the last billing run. Those boundaries may be several days apart. A billing-run total can therefore omit earned revenue even when it is accurate for the cycle it covers.
A system without a point-in-time usage snapshot forces finance to estimate the missing consumption. That introduces uncertainty even for products whose contract terms would otherwise support the right-to-invoice expedient. The problem begins with the measurement boundary. A platform that processes usage events in real time and produces totals as of a specified timestamp can supply the required evidence. Daily batches or billing-cycle totals leave a stretch of time that finance must account for by hand.
When closing the books, finance teams must sort invoices around period-end by the service period they cover. Unbilled amounts must be accrued and the accrual cleared when the invoice is raised, without recognizing revenue again. Annual seat true-ups require allocation between current and prior periods. Credit notes issued after close also need review when they concern problems that existed before period-end and may require a prior-period adjustment.
Separate billing paths make this work harder to reconcile. If subscriptions, overages, and prepaid credits sit in different systems, no single system holds the complete contract picture. The closing balance then depends on assembling those records correctly. This is more than administrative friction because an omission or mismatch can flow directly into unbilled revenue.
What ASC 606 requires companies to disclose about unbilled revenue and remaining performance obligations
The contract-balance roll-forward links the work of closing the books to what the company discloses externally. It shows how balances move through the period and gives auditors a basis for testing them against contract records, billing transactions, and usage evidence. The closing figure cannot stand alone. Its support must explain the movement from earned but unbilled amounts to receivables, as well as the movement in deferred revenue as services are delivered.
ASC 606 also requires revenue disaggregation, remaining performance obligations, and significant judgments. For a metered product, disaggregation typically separates subscription base fees from usage-based overages and distinguishes product lines. Those categories show how the timing of revenue and the uncertainty around it differ. Significant-judgment disclosures explain the methods and assumptions used to determine and allocate the transaction price, including variable consideration estimates, the constraint methodology, and breakage calculations.
Remaining performance obligations concern the transaction price allocated to obligations not yet satisfied and the expected timing of recognition. They are especially relevant to multi-year minimum commitments. Salesforce defines RPO as “contracted revenue that has not yet been recognized, which includes unearned revenue and unbilled amounts that will be recognized as revenue in future periods.” The reference to future recognition is important. Those unbilled contracted amounts are not the same as revenue already earned but awaiting an invoice, although both require accurate contract records and allocation.
For minimum commitments with usage upside, the RPO calculation also requires constraint discipline. Finance must separate the committed future revenue from the variable amounts that are part of the transaction price. Management metrics require another clear boundary. ARR, NRR, and churn rate do not substitute for GAAP revenue, so stakeholders need explanations of the differences, including the distinction between “Contracted ARR” and “Recognized Revenue” and the separate deferred revenue backlog.
The audit errors finance teams make at period-end and how auditors find them
Invoice-date recognition assigns revenue to the billing period. Auditors find it by sorting invoices around period-end by service period and comparing them with the revenue schedule.
Billing-run cut-off leaves consumption after the last run unrecorded or supported only by an estimate. Auditors test usage-based accruals against a point-in-time extract through the last day of the accounting period.
Gross presentation can overstate both assets and liabilities when contract assets and deferred revenue should be netted per contract. The audit test compares the reported balances with the underlying contract position.
Revenue may be recognized too early for contracts that were not approved and enforceable at period-end. Auditors check contract approval and enforceability rather than rely on a closed-won CRM status, and leave out unsigned or incomplete arrangements that fail to meet the contract-identification requirements.
Early renewal recognition starts revenue at signature, before the renewal term begins. Comparing the revenue schedule with the service dates identifies amounts that belong in deferred revenue until the new term begins.
Review of commission treatment identifies immediate commission expense that bypasses capitalization under ASC 340-40.
Multi-year prepayments can omit a required financing assessment. Comparing payment and delivery timing identifies arrangements outside the practical expedient for a gap of one year or less, including a three-year prepaid deal.
Contract amendments can leave the original revenue schedule running after an upgrade, downgrade, or co-term. Comparing the amendment with the revised allocation shows whether the transaction price was reallocated.
With weak audit trails, auditors cannot follow the contract through to the revenue schedule and then to the journal entry. For metered products, auditors also look for the usage log supporting the unbilled balance.
Expiry-based breakage recognition bypasses the proportional estimate across the usage period. Testing the recognition pattern against historical redemption data exposes that difference.
Credit notes issued after the period can show that problems were already there before close. Auditors check them to see if prior-period adjustments are needed and test the deferred revenue roll-forward against the billing system’s transaction log.
What billing infrastructure needs to do to make period-end close defensible
These audit tests call for billing systems that can do the following. The first is an auditable usage snapshot as of any calendar timestamp, covering consumption through the accounting boundary. The second is an event-level trail. Each usage event must connect to the contract, performance obligation, revenue schedule, and journal entry so that the contract-balance roll-forward can be tested against its underlying evidence.
The system must also represent the economics of the contract without fragmenting them across separate billing paths. Minimum commitments, overages, declining-rate tiers, and prepaid credit balances need to be modeled together. Historical redemption data must support breakage estimation rather than requiring reconstruction in a spreadsheet at close. Contract modifications must lead to transaction-price reallocation for upgrades, downgrades, and co-terms rather than let the original schedule run on unchanged.
The build-versus-buy decision does not remove these obligations. When a point-in-time snapshot capability is built in-house, engineers must keep it working through maintenance, upgrades, debugging, and pricing changes. A new tier or usage dimension can therefore require an engineering ticket before the accounting can follow. The chosen approach must supply dependable close evidence across those changes regardless of whether the company owns the code.
For finance teams, the practical test is concrete. If producing the period-end unbilled revenue balance requires pulling data from more than one system, reconciling it manually, or accepting an estimate because the billing system cannot produce a point-in-time total, the infrastructure is not built for the accounting requirements of a metered product.