Accrued Expenses vs Accounts Payable in SaaS Finance
Invoice arrival sets the classification, and usage data sets the estimate.
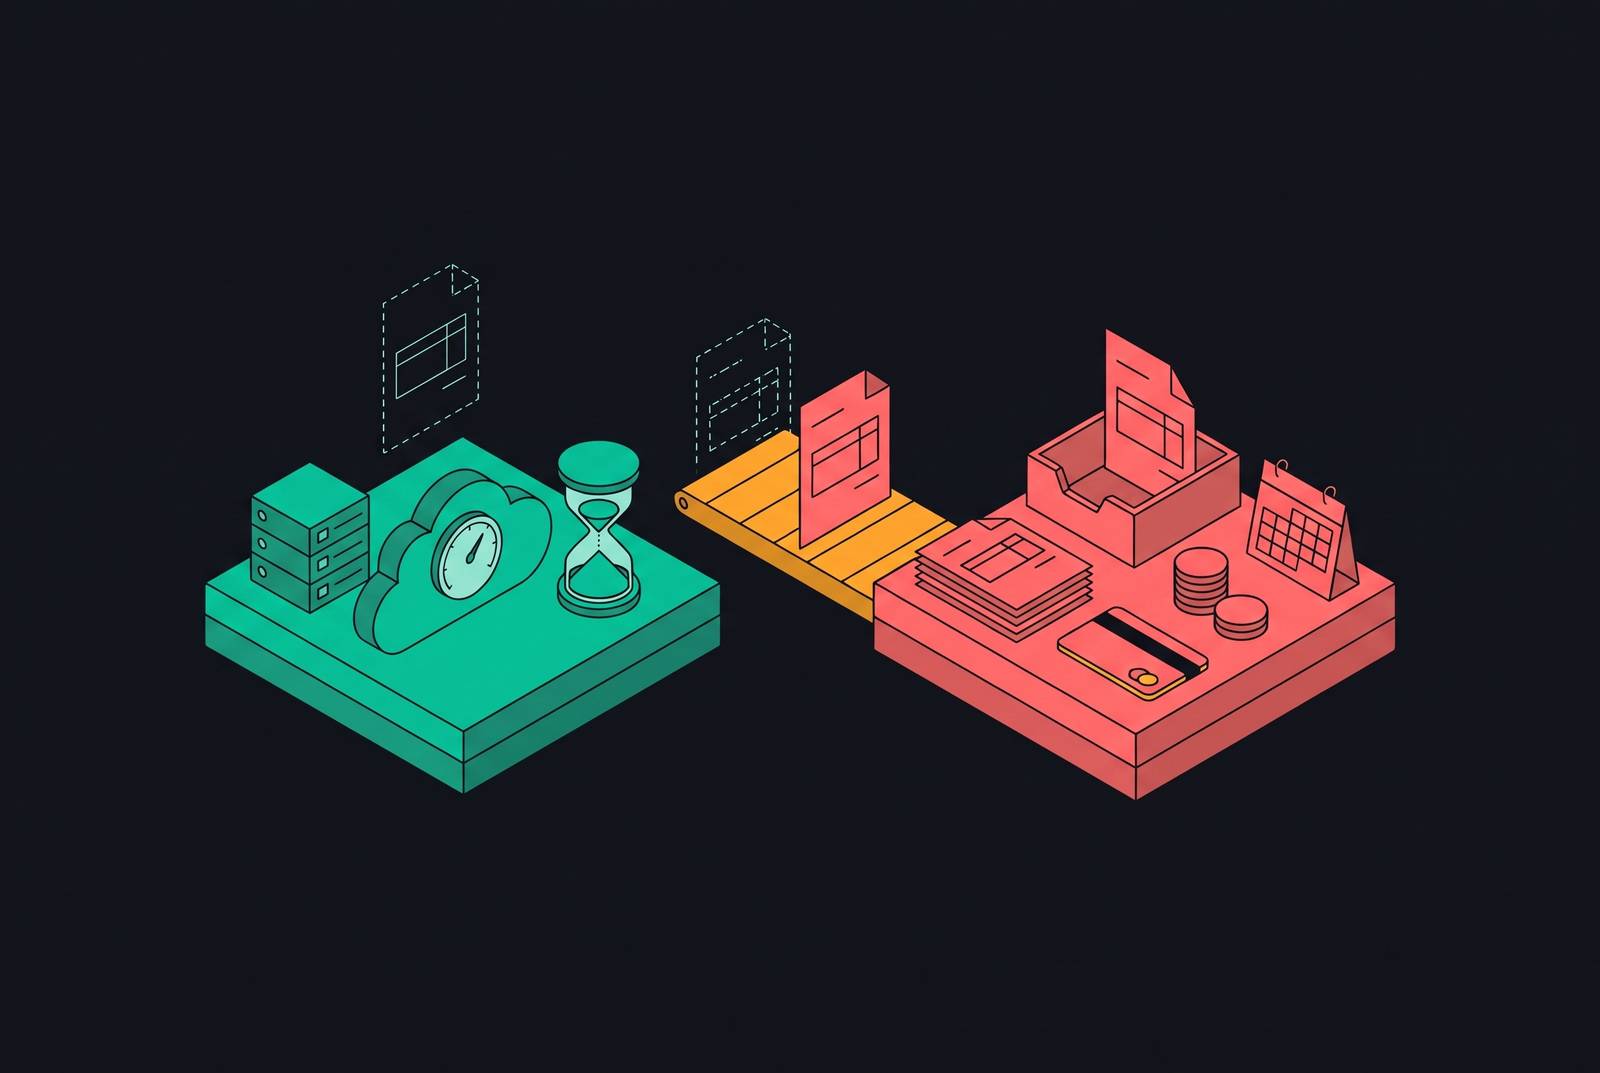
Accrued expenses and accounts payable in SaaS finance differ primarily by whether a vendor invoice has arrived and been recorded. Keeping that distinction separate from the timing of expense recognition is essential to accurate financial statements, cash flow forecasts, and period-end closes. For variable cloud and AI costs, doing so requires more than journal entries. It requires timely consumption data and a controlled path from estimate to recorded invoice.
Why invoice arrival — not service delivery — determines how a SaaS liability is classified
An incurred vendor obligation is an accrued expense before the invoice arrives and accounts payable after the invoice is received and recorded. Service delivery determines when the expense belongs. Confusing them makes invoice receipt the trigger for recognizing a cost that may belong to an earlier period.
Under accrual accounting, both are current liabilities on the balance sheet. Accounts payable, or AP, records a fixed, invoice-confirmed amount, while an accrual records an internally calculated amount that may need adjustment. Finance must therefore track the classification deliberately. When that distinction is lost, obligations can be misstated, expenses can fall into the wrong period, and cash flow forecasts can reflect the wrong liability profile.
How the matching principle creates the accrued expense entry and what reversal prevents
The matching principle requires costs to be recognized in the period in which the business received the benefit, regardless of when the invoice arrives or cash moves. At period-end, finance debits the relevant expense account and credits accrued liabilities, dating the entry on the last day of the accounting period. Without an invoice, the amount is an estimate supported by the available information.
The next entry reverses that temporary recognition at the start of the following period. Finance debits accrued liabilities and credits the expense account, flipping the original entry. This clears the way for the invoice. When the actual bill posts to AP, it does not leave the original accrual and the invoiced obligation recorded simultaneously. If the invoice differs from the estimate, the difference must be accounted for before the payable is settled.
This sequence applies to costs that become vendor payables, but not every accrual takes that route. Payroll, bonuses, interest, and taxes can be paid directly without going through the vendor subledger. The accounting must connect the original estimate with the eventual invoice or payment, rather than assume that every accrued balance will become AP.
Where SaaS costs actually fall — which liabilities are almost always accruals and which go straight to AP
Cloud infrastructure and usage-based vendor fees generally belong on the accrual-first side of the SaaS close. AWS, GCP, and Azure services billed in arrears are consumed throughout the month, with the invoice arriving early in the following month. API consumption, AI inference costs, and metered SaaS tools follow the same pattern, although their invoices may lag consumption by weeks.
Development, legal, and audit work completed before the contractor sends an invoice creates a pre-invoice obligation. Wages earned before period-end but paid after it are payroll accruals that never go through the vendor AP subledger. Interest and taxes also come from calculations made within the business. The absence of a vendor bill is expected in these categories.
The straight-to-AP side includes software subscriptions with upfront invoices, office and equipment purchases accompanied by invoices, and contractor work billed before or at close. Invoice timing remains the deciding variable here. A contractor cost can therefore fall on either side, depending on whether the bill has arrived when finance closes the period. Recording the payable does not make invoice timing a substitute for determining the expense period.
The practical response is a standing monthly checklist organized by cost category. Contracts, usage data, and past patterns help finance estimate costs when the bills have yet to arrive. These categories recur from month to month. A category-based process makes their review routine while preserving the distinction between an accrued obligation and one already recorded in AP.
Why usage-based and AI consumption pricing turns routine accruals into a persistent estimation problem
Fixed vendor fees are fairly easy to estimate for accruals because the amount in the contract stays the same. With consumption pricing, the amount can change from one close to the next. AI inference, API calls, GPU-minutes, and similar costs accumulate in real time but are invoiced in arrears, monthly at minimum and sometimes quarterly. Finance must reconstruct the period’s cost from usage logs, vendor dashboards, and contractual rate cards before a formal billing document arrives.
With AI-driven spending, prior-period run rates are less reliable as a way to work out that cost. Consumption can fluctuate sharply as product usage changes. An estimate based mostly on the previous period may miss how much was used in the current period, even if the vendor relationship and pricing model are the same. Without reliable usage data, finance can over-accrue and overstate liabilities or under-accrue and understate them. The later true-up then changes the following period’s expense line.
Waiting for the invoice moves the expense into a later period. Posting the cost only when the bill arrives violates the matching principle when the service belongs to the period already closed. This is a common failure in early-stage SaaS finance, where invoice receipt can become the default trigger for all expense recognition.
Because the amount is estimated rather than invoice-confirmed, its supporting evidence also becomes important during audit review. A defensible accrual needs a traceable connection between consumption, pricing, and the accounting period. Estimation itself is not an accounting failure. The weakness arises when finance cannot explain the basis of the amount or reconcile it to the later invoice without reconstructing the calculation from memory.
What reliable accrual estimates for metered costs actually require from the finance and engineering stack
A reliable metered-cost accrual requires cumulative usage for the period and the rates that apply to that usage. Finance also needs to know which rate tier applies, what the committed minimums and overage rates are, and whether usage crossed any pricing threshold during the period. Volume alone is not a cost estimate. The calculation must link how much was consumed to the contract terms that set what the vendor will charge.
That connection depends on when the usage data becomes available. When metering data comes in batches or arrives late, finance must estimate from a period-end total that leaves out some usage, so the later true-up is larger and harder to predict. Real-time or near-real-time data narrows that gap. A point-in-time consumption figure on the last day of the period can closely approximate the usage that the invoice will include. For AI products, where token and GPU-minute consumption can spike sharply, stale data can make an estimate materially wrong within hours.
Internal tracking built around spreadsheets or basic pipelines may not produce the granular, deduplicated, period-accurate consumption data a defensible accrual requires. Purpose-built metering infrastructure addresses that requirement by ingesting events at speed and aggregating them by billing period. The finance outcome is the relevant test. Technical ingestion and aggregation capabilities support a billing workflow and produce usable evidence for the close.
Access is as important as the underlying calculation. Finance needs usage data in a form it can use, rather than information available only through engineering or product teams. Real-time dashboards and in-period consumption alerts support that access while also helping customers avoid bill shock. For finance, they allow estimates to be monitored throughout the period.
The double-counting and misclassification errors that most commonly surface at month-end close
Double-counting occurs when finance posts a month-end accrual and then records the next period’s invoice without reversing the accrual. The original estimate remains while AP records the actual bill. Both liabilities represent the same underlying cost. Expenses and liabilities are overstated because the estimate has not been cleared as part of recording the invoice. This can happen even when each entry looks right on its own.
An omitted accrual is the opposite failure. The service has been received, but no invoice has arrived and no expense entry is made. The original period consequently shows understated liabilities and overstated profit, while the expense appears when the bill arrives later. Invoice-led workflows are particularly exposed to this omission. They apply cash-basis thinking inside an accrual system by treating the absence of a bill as a reason to defer recognition.
Wrong-period recognition differs from outright omission because an accrual exists, but its date follows the invoice, placing the cost outside the service period. Reconciliation also fails when an estimate is materially wrong and finance does not adjust it to match the invoice. The unrecorded true-up can leave a residual accrued liability with no corresponding obligation. These failures require more than confirming that an expense entry exists.
Finance spends the first days of the new period reconciling obligations that should already have been cleared or adjusted. The more variable-cost vendors the business has, the more work this takes. Unsupported estimates and unexplained residuals can also require further explanation during audit review, but the immediate operating problem is recurring reconciliation work. Each unresolved item makes the next close harder to complete cleanly.
The period-end controls that prevent misclassification from becoming a recurring close problem
Cloud infrastructure, AI API costs, contractor engagements, payroll, and interest should receive required period-end review independent of invoice arrival. Where an obligation remains unbilled, the checklist should trigger the accrual entry. Where an invoice is already recorded, the same review should prevent a duplicate accrual. Consistent coverage also improves cash flow planning and reveals cost patterns that can inform later estimates.
Automatic reversals should enforce the transition into the next period. Configuring accrual entries to reverse at its start removes dependence on a manual step during a busy close. Automation alone does not complete the reconciliation. Accrual-to-AP lifecycle tracking should connect each later invoice to its earlier estimate, enforce the necessary adjustment, and clear the accrued balance.
For variable-cost vendors, finance should be able to get consumption data directly before close rather than go through engineering or product to get it. The required output is a period-to-date report that finance can pull on the last day of the period. That access makes actual usage the foundation of the estimate. Prior-period run rates can then inform the calculation without standing in for current consumption. Billing infrastructure supports the close when it exposes this information before the invoice is generated.
Documentation should keep a record of what went into each estimate, including vendor usage logs, contractual rate cards, and prior invoices. Review should not depend on anyone’s memory. Traceable calculations make it possible to explain the estimate, account for the later difference, and support investor reporting, board materials, and diligence. Together, these controls replace the first-week reconciliation scramble with a repeatable process that produces financial statements reflecting the costs of the period just closed.