Annual Recurring Revenue Calculation for Usage-Heavy SaaS
Usage-based revenue moves monthly, making standard ARR calculations unreliable.
A finance team runs the standard ARR formula on a usage-heavy book of business and gets a different answer depending on which month it picks as the base. That inconsistency is the first sign that annual recurring revenue, as a concept, is a revenue-classification problem for usage-driven companies, not a formula to look up and apply. The MRR × 12 approach was built for a world where a contract guarantees a fixed monthly amount: multiply it by 12, and the annual figure is a commitment, not a guess. Usage-based revenue is calculated in arrears from actual consumption, so the monthly figure moves with customer behavior, and any annualized total built on top of it is an estimate the business has not locked in.
The classification tension between contractually fixed revenue and predictable-but-variable usage revenue produces nearly every disagreement finance teams have about usage-based ARR, and finance teams have to choose a defensible position between those two poles, a choice that carries consequences well beyond the metric itself.
The distinction matters because customers can and do vary their consumption from one month to the next. Usage-based revenue that a company generates in one period may or may not recur in the next, and treating it as functionally identical to committed subscription revenue obscures how stable the business actually is. That obscuring effect does not stay contained to the ARR line. Net revenue retention, churn, and expansion figures are all built on top of ARR as a base, so when ARR is noisy at its foundation, every metric derived from it inherits that noise. Leadership ends up making growth decisions based on a trajectory that may not reflect what is actually happening with customers.
The predictability principle: which usage revenue belongs in ARR at all
The question that should govern inclusion is whether a given revenue stream is predictable, and predictability has to be assessed at the portfolio level rather than customer by customer. What matters is whether the aggregate revenue generated by a large enough base of usage customers behaves consistently over time, because that aggregate stability is what makes a decision to include usage in ARR defensible.
The practical test follows directly from that principle: examine whether aggregate monthly usage revenue has moved consistently across the trailing period under review. To answer that question well, you need actual visibility into consumption patterns across the installed base, tracked without manual reconciliation between systems. Real-time usage dashboards and spend visibility from metering platforms give finance teams the data to validate, or disprove, whether usage truly belongs in recurring revenue.
Segmentation sharpens the test further. A sound inclusion strategy treats these two populations differently: it folds the predictable segment into ARR while tracking the erratic segment separately. A customer burning through a large volume of API credits every month, with no minimum commitment attached, contributes nothing to committed ARR by definition, no matter how large the dollar figure looks in a given month. That consumption belongs in a usage run rate metric tracked alongside ARR, not blended into the figure investors read as durable.
ARR remains a company-defined metric rather than a line item governed by a single accounting standard. A company that combines annualized subscription contract value with annualized on-demand billings is making a legitimate choice, as long as the disclosure accompanying that figure makes the composition explicit. That gap suggests the predictability principle becomes easier to apply, and the inclusion decision easier to defend, once a usage-based business has enough scale and history to demonstrate aggregate stability.
When each annualization method is defensible
Once a finance team has decided which usage revenue qualifies for inclusion, the next decision is how to annualize it, and no single formula is correct across every usage pattern. The right method depends on whether consumption is stable, seasonal, or trending upward or downward, and applying the wrong one produces a figure that flatters or understates the business relative to its real trajectory.
Two methods dominate practice. Multiplying the most recent month by 12 amplifies whatever happened in that single month, spike or trough, into a full year's figure. Multiplying the trailing three months by four is the more common approach for usage-based ARR specifically because it smooths short-term volatility while still reflecting where the business is trending.
Public companies illustrate the range of defensible choices. Snowflake and Twilio do not report ARR at all, citing the difficulty of forecasting revenue from fluctuating consumption. That omission is itself informative: it signals that usage-based revenue has no universally clean formula for annualization, rather than suggesting those companies have found one and kept it private.
Whichever method a company adopts, the discipline that matters most is consistency. When that data sits fragmented across multiple systems, or requires manual export before it can be analyzed, finance teams lose the ability to apply a chosen method consistently, and consolidated metering infrastructure that surfaces usage trends by segment in real time removes that friction.
Handling the three revenue components in a hybrid contract without double-counting
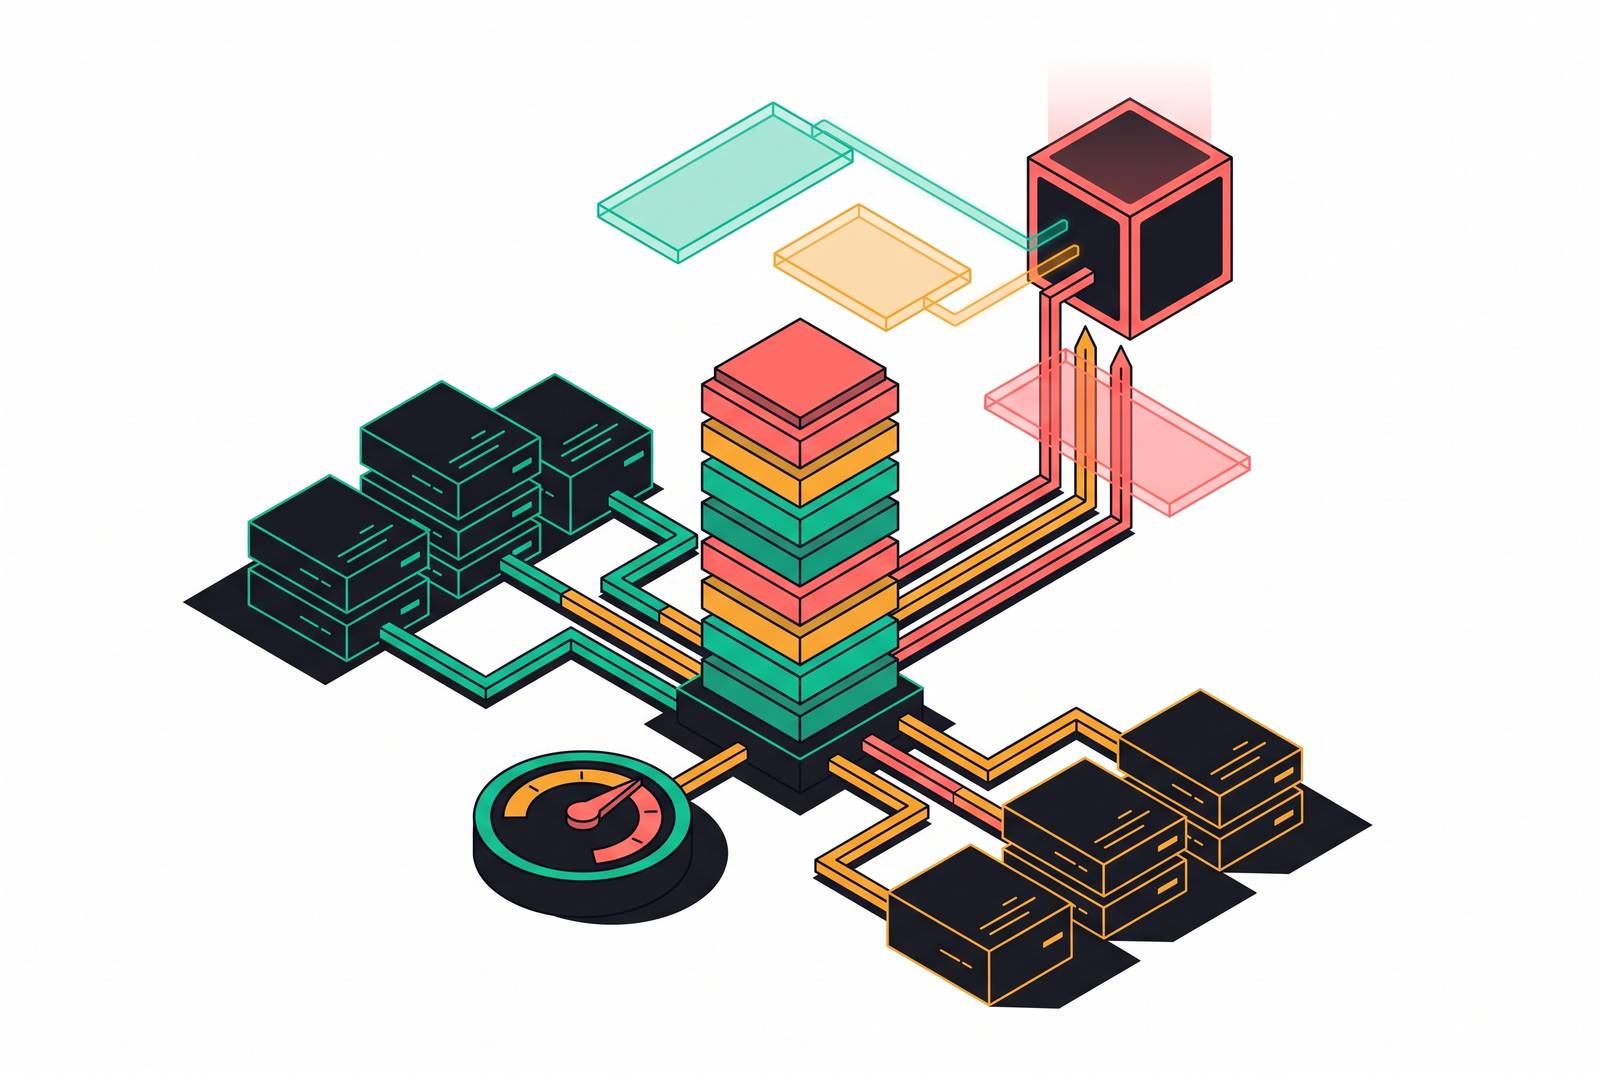
Hybrid contracts combine three distinct components, and reporting them accurately requires keeping them separate in the ARR figure. The components are a fixed subscription fee, which is genuinely recurring; a minimum usage commitment, which is contractual but not driven by actual consumption; and variable overage above that minimum, which is neither fixed nor committed. Summing all three without care counts some of the same dollars more than once.
A worked example makes the mechanism concrete. Consider a noncancelable annual agreement that combines a platform subscription with quarterly AI consumption commitments, where unused commitment does not roll over and overage is billed quarterly above each threshold. The correct report separates all three components: the fixed platform fee, the committed minimum, and the overage. The annualized usage run rate should reflect only consumption above the committed minimum, and nothing more.
Minimum commitments carry their own classification problem on top of this. A commitment is contractual, but that does not make it automatically recurring. The ARR policy has to specify which treatment applies to which contract type and disclose that choice. The more useful approach reports usage separately as an annualized usage revenue run rate, discloses the measurement window behind that figure, and presents it alongside fixed recurring fees.
Two reporting lenses keep these components from collapsing into noise: durability, meaning how dependent a given revenue stream is on future consumption continuing, and product mix, meaning how much of total revenue comes from AI features compared with conventional software. A single blended ARR number cannot answer either question. Billing infrastructure built specifically for hybrid pricing, Flexprice among it, prevents the error at the source by enforcing the split at billing time, so the ARR calculation downstream inherits data that is already separated rather than requiring finance to untangle it after the fact.
ARR components and ASC 606 revenue recognition in usage-heavy models
ARR is a management metric. It has never been a recognized-revenue figure under any accounting standard, and the gap between the two has to be documented and bridged every period. Treating ARR and recognized revenue as interchangeable is the most common structural error in hybrid-contract accounting, and it produces errors that appear both in financial reporting and in audit exposure.
Under ASC 606, when hybrid pricing combines fixed fees with usage, each component is recognized on a different timeline. The fixed portion is recognized ratably over the contract term, while the usage portion is recognized as it is incurred. Both components can sit inside the same ARR line item while following entirely different recognition timing, and that mismatch is precisely where confusion between the two concepts tends to originate.
The variable consideration constraint under ASC 606 adds a second layer finance teams cannot skip. Tagging billing lines for ARR reporting purposes is a management-reporting exercise, and it does not by itself determine performance obligations or revenue allocation under SaaS revenue recognition guidance. Keeping those two processes separate, one for management reporting, one for recognized revenue, is what a well-built SaaS P&L depends on when subscription and usage-based revenue carry different margin profiles. A documented bridge, refreshed every period, explaining the specific differences between ARR and recognized revenue is what keeps an ARR figure traceable and explainable when diligence arrives.
Building an ARR policy that survives investor diligence and board review
An ARR methodology that exists only in a spreadsheet, or only in one finance leader's head, functions as a liability. Any metric that cannot be reproduced consistently across periods, and explained clearly to an auditor, will be challenged during diligence, and that challenge tends to arrive at the worst possible moment in a fundraising or acquisition process.
A formal written policy has to define explicitly which revenue streams are included and which are excluded: usage fees, monthly plans, professional services, pilot programs, all of it named specifically. That document, not a summary slide prepared for a board meeting, is the definitive reference for every period's reporting. Whenever ARR appears in a reporting document, the methodology behind it belongs in a footnote or appendix: the annualization window used for usage revenue, the customer segments included or excluded, and how minimum commitments are classified.
Usage-based ARR calculations should rest on normalized historical data, not optimistic sales forecasts. Changing the annualization window, or the inclusion criteria, between periods in order to produce a better-looking number is the fastest route to losing investor trust, so the policy needs to specify not just how ARR gets calculated but when and how changes to that methodology are permitted and disclosed. The policy exists, ultimately, so that a future acquirer, investor, or auditor can reconstruct every ARR figure directly from the underlying billing data, without requiring the CFO to walk them through it by hand.
What the billing infrastructure underneath ARR reporting must do
A written ARR policy is only as reliable as the billing system generating the data behind it. A policy for hybrid pricing requires infrastructure that can tag every revenue line by type, fixed fee, committed minimum, and usage above minimum, because a system that cannot distinguish between them forces finance to do that separation by hand every period, with the reconciliation errors that manual work reliably introduces.
Separating revenue by durability requires billing systems, contract management, and revenue recognition processes capable of tagging revenue at the line-item level. Companies running a separate metering tool alongside a separate billing tool face a structural problem on top of that: consumption data from one system has to be reconciled against invoice data from the other before any ARR tagging can even begin, and that reconciliation step introduces both latency and error into every period close.
Real-time metering has a direct bearing on ARR accuracy. Prepaid credit wallets add a further wrinkle: a customer purchasing a block of credits upfront creates a liability that draws down as consumption occurs, and the billing system has to track the wallet balance, recognize revenue only as credits are actually consumed, and reflect the consumed portion, not the full upfront purchase, in the usage run rate.
Pricing agility is the final structural requirement. Billing infrastructure built for usage-based and hybrid models, which is the specific problem Flexprice is built around, addresses this at the architecture level: ingesting usage events as they happen, tagging revenue lines by type at the point of billing rather than after the fact, and managing wallet mechanics for prepaid credit balances, so finance and product teams can adjust pricing constructs without routing every change through an engineering sprint. That architecture does not replace the judgment calls described earlier in this piece. It makes those judgment calls executable consistently, period after period, against clean data.
Keeping ARR honest as the business scales and the pricing model evolves
ARR methodology is not a decision a finance team makes once and shelves. As pricing complexity compounds, credits layering on top of usage, usage layering on top of subscriptions, enterprise commitments layering on top of either, the classification rules and annualization choices set at the outset will need revisiting. A company's handling of those revisions shapes whether ARR continues to function as a useful signal or gradually drifts into noise.
Some changes to a pricing model rise to the level of a methodology change and have to be treated that way. Net revenue retention offers a useful check on the underlying quality of the ARR figure feeding it. But if the ARR figure already inflated those usage numbers before NRR was calculated, the retention metric will look artificially compressed, masking the very expansion it exists to capture.
The investor credibility stake sits exactly at the gap between contracted ARR and recognized revenue, which is precisely where diligence tends to probe hardest. A company whose ARR definition has drifted without documentation, whose annualization method changed without disclosure, or whose usage figures quietly include uncommitted consumption, will face questions capable of slowing or derailing a raise. The practical cadence that prevents this is straightforward: review the ARR policy at least annually, test the chosen annualization method against actual recognized revenue from the prior period, and document any adjustments along with the reasoning for why the change better reflects revenue durability. That discipline, repeated period after period, is what turns an ARR methodology from a one-time exercise into a durable reporting asset. The infrastructure behind ARR can make the right numbers available. Only sustained governance keeps them honest.